Not the Shortage You Remember
If you lived through the 2020 to 2023 chip shortage, you probably remember it as a pandemic problem. Factories shut down, shipping got stuck, and supply couldn’t keep up with sudden demand. What’s happening in 2026 looks similar from the outside — phones cost more, and there’s less to go around — but the cause is completely different. This time, nobody broke the supply chain. Someone chose to redirect it.
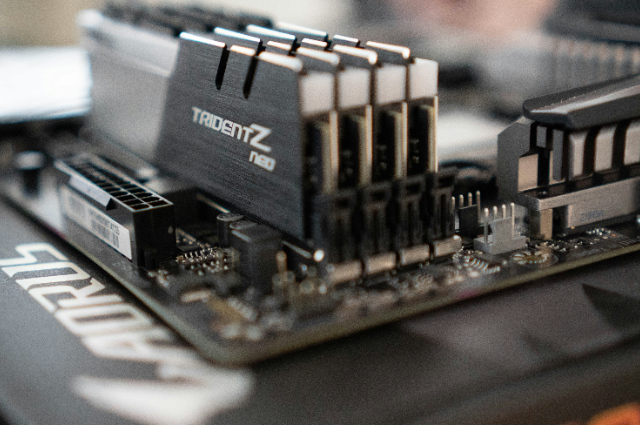
The tech press has started calling it “RAMmageddon” or the “RAMpocalypse,” and neither name is much of an exaggeration. This is a memory chip shortage, meaning it hits DRAM and NAND flash — the components responsible for how much your phone can store and how fast it runs. And it isn’t accidental. It’s the direct result of a business decision made by the handful of companies that control almost all of the world’s memory chip production.
Where All the Memory Actually Went
Three companies — Samsung, SK Hynix, and Micron — control more than 95 per cent of global DRAM production. For decades, their factories mostly served phone and PC makers. That’s no longer true. Over the past two years, all three have been steadily shifting their factory capacity away from ordinary phone-grade memory and toward something called High Bandwidth Memory, or HBM — a specialised, far more expensive type of memory built specifically for the AI accelerators powering data centres.
The economics explain why. Every gigabyte of HBM eats up roughly three times the wafer space that a gigabyte of standard DDR5 memory does, and HBM sells at a steep premium. When a chipmaker has a fixed amount of factory capacity and one product line is dramatically more profitable than another, the choice isn’t really a choice at all. It’s simple math, repeated across every factory those three companies operate.
The buyers driving this shift are the hyperscalers: Google, Meta, Microsoft, and Amazon, along with the AI chip designers building products for them. These companies are pouring enormous amounts of money into AI infrastructure — combined spending across the sector is estimated to reach roughly $650 billion in 2026, up from around $360 billion the year before. A single high-end AI server rack can contain over 13 terabytes of RAM, which is roughly the equivalent of the memory found in a thousand smartphones combined. To secure the supply they need at that scale, hyperscalers have locked in years of production through premium, long-term contracts directly with the chipmakers. That leaves phone manufacturers competing for whatever capacity is left over — and there isn’t much of it.
The Numbers Behind the Squeeze
The scale of the price increases has been extreme. DRAM spot prices have surged by roughly 700 per cent over the past year, according to industry reporting, and one analyst described prices as going “parabolic” rather than simply rising. Wholesale smartphone prices jumped 14 per cent in the first quarter of 2026 alone.
On the shipment side, the picture is just as stark. Counterpoint Research now expects global smartphone shipments to fall around 13.9 per cent for the full year, down to roughly 1.08 billion units — the steepest annual decline the smartphone industry has ever recorded. IDC’s own projection lands in a similar range, around 13.9 per cent as well. The second quarter of 2026 alone saw shipment volumes drop to their lowest level since 2013.
Budget Brands Are Taking the Hit
This shortage isn’t landing evenly. Brands that sell high volumes of low-margin phones are being hit the hardest, because memory now makes up a much bigger share of what it costs them to build a device, and they have far less room to absorb the increase without losing customers entirely.
Transsion, which dominates budget smartphone sales across Africa and parts of Asia, has already reported a 54 per cent drop in its 2025 net profit and cut its annual shipment target by 40 per cent. Counterpoint separately forecasts Transsion’s full-year 2026 shipments could fall by as much as 32 per cent. Xiaomi isn’t far behind — its shipments fell 19 per cent year-over-year in the first quarter alone, with a projected 28 per cent decline for the full year. Oppo and Vivo have also cut their targets sharply. In India specifically, the sub-$100 smartphone segment collapsed by 59 per cent year-on-year in the first quarter.
Apple and Samsung are telling a very different story. Both locked in supply agreements earlier than competitors and operate at higher price points, giving them more room to absorb rising costs. Counterpoint expects Apple’s 2026 shipments to hold roughly flat before growing again in 2027, with its global market share climbing to a record high. Samsung, meanwhile, is projected to see only a 4 per cent shipment decline for the year — far smaller than the broader market — partly because its own semiconductor division is profiting from the very same AI memory boom squeezing its phone-making rivals.
When Does It End?
Estimates vary quite a bit, which says something on its own about how uncertain this situation really is. Some analysts point to 2027 or 2028 as when new memory production capacity — including new fabs from Micron in Idaho and New York, SK Hynix in Indiana, and Samsung in Texas — could start easing supply. Others are far less optimistic. SK Group’s chairman has said the shortage could last until 2030. IDC’s own forecast anticipates supply growth well below historical norms through at least 2026, with real relief unlikely before 2027 or later.
It’s Not Just Phones
While smartphones are the most visible casualty, the same memory squeeze is spreading into other products entirely. PC makers including Dell, Lenovo, HP, Acer, and Asus have all warned of price hikes in the range of 15 to 20 per cent, arriving at an especially awkward moment given the industry’s simultaneous push toward memory-hungry “AI PCs.” Automakers are watching closely too, since modern vehicles depend on many of the same memory components for everything from infotainment systems to driver-assistance features. What started as a quiet reallocation of factory capacity toward AI data centres has, in less than two years, become a supply problem touching almost every category of consumer electronics — and there’s no firm date yet for when that pressure will let up.
References:
- Wikipedia. “2025–present global memory supply shortage.”
- Tech Insider. “2026 Memory Chip Shortage: SK Hynix Warns It May Last Past 2030.”
- IDC. “Global Memory Shortage Crisis: Market Analysis and the Potential Impact on the Smartphone and PC Markets in 2026,” February 10, 2026.
- Adwaitx. “Memory Chip Shortage 2026: How RAMmageddon Impacts Tech Giants,” February 16, 2026.
- BigGo Finance. “Memory Crunch Freezes Smartphone Market: 2026 Shipments Seen Plunging 13.9%,” June 5, 2026.
- Memeburn. “Memory Crisis: Smartphone Market Is Getting 15% Shrink in 2026,” June 19, 2026.
- Memeburn. “Smartphone Market Decline 2026: Why Phones Cost More & What’s Next,” June 3, 2026.
- Tech Times. “Smartphone Market Hits 13-Year Q2 Low as AI Memory War Erases Affordable Tier,” July 14, 2026.
- BigGo Finance. “Memory Price Surge Splits Smartphone Market: Q2 Global Shipments Hit 13-Year Low,” July 2026.
- Unibetter. “RAM Memory Shortage 2026 Guide: Price Trend and Market Outlook Analysis.”